Reviewed: 28 July 2026
A reliable Vietnam payroll cycle starts before anyone applies a formula. The company first needs approved attendance, employee changes, pay instructions and tax or insurance status. The calculation then needs an independent review, company approval, controlled payment and a post-payroll reconciliation.
This guide maps those hand-offs into one monthly process. It is designed for employers that need to understand what their Vietnamese team, headquarters and payroll provider should each deliver.
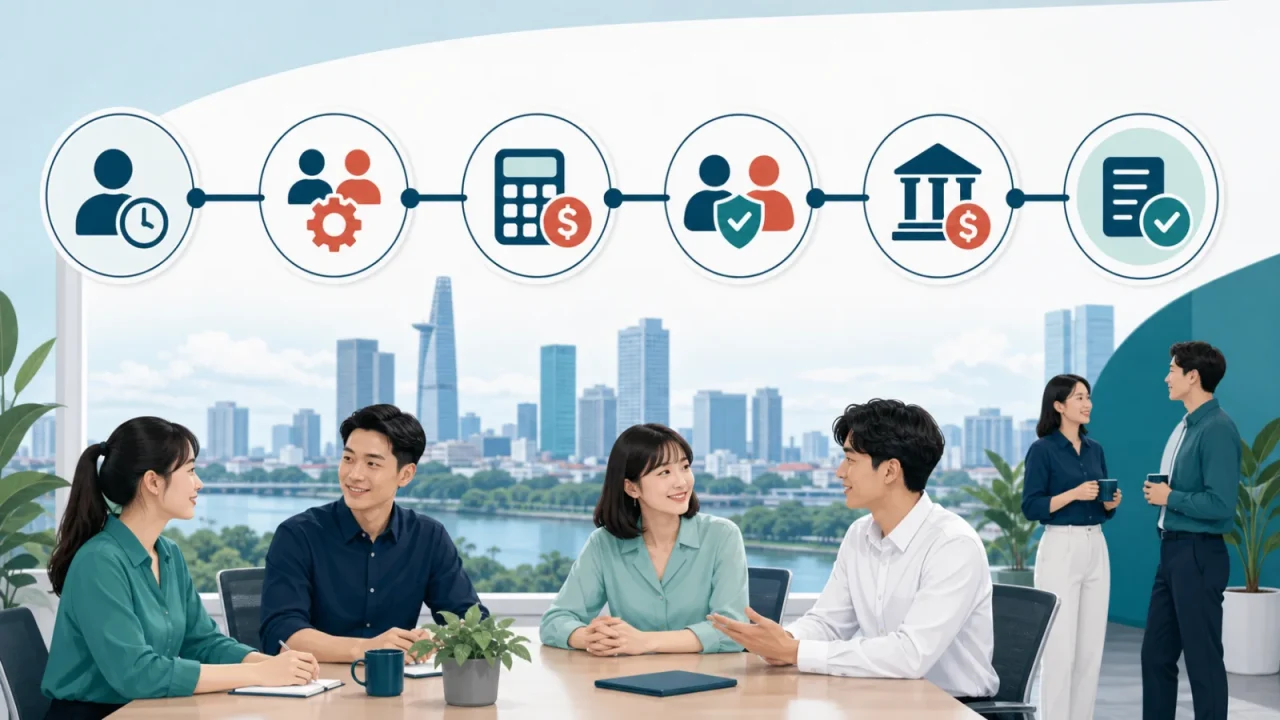
The monthly payroll process at a glance
| Stage | Core work | Control evidence |
|---|---|---|
| 1. Cut-off | Close attendance and collect approved employee changes | Cut-off checklist and approval record |
| 2. Input validation | Check completeness, duplicates and unusual changes | Exception list and source-document register |
| 3. Gross-to-net | Calculate earnings, overtime, benefits, insurance, PIT and net pay | Calculation file with locked assumptions |
| 4. Review | Compare headcount, total cost and employee variances | Reviewer sign-off and query log |
| 5. Approval and payment | Company approves payroll, pays employees and completes agreed filings | Approval, bank file and submission receipts |
| 6. Reconciliation | Match payroll, bank, accounting and statutory balances | Reconciliation and open-item list |
1. Set a cut-off and change-control rule
Before each cycle, confirm the pay date and work backwards to the attendance cut-off, data deadline, first calculation, query window and final approval. A practical model for a stable monthly cycle is:
| Timing | Activity |
|---|---|
| T-10 business days | Attendance and variable-pay data submitted |
| T-7 | First payroll and exception report issued |
| T-5 | Company review and correction requests completed |
| T-3 | Final payroll, payslips and bank data delivered |
| T | Salary paid |
| After T | Reconciliation and approved corrections |
This is a planning example, not a statutory timetable. The actual calendar must fit the employment contracts, company pay rules, bank processing and statutory filing cycle. Late inputs should not be silently overwritten; log the reason, approver and treatment in the current or next payroll.
2. Validate attendance and employee changes
Attendance should show ordinary hours, overtime by type, night work, paid and unpaid leave, absence and shift information where relevant. The Labour Code sets limits on normal working time and overtime and provides different minimum premium rules for ordinary days, weekly rest days, public holidays and night work. The system should therefore preserve the category and approval behind each hour rather than sending only a monthly total.
Employee-change inputs usually include joiners, leavers, salary adjustments, allowances, bonuses, deductions, bank changes, dependant registrations and insurance changes. Use an effective date and an authorised source for every change.
3. Build and review gross-to-net
Gross-to-net is the bridge from contractual and approved earnings to the amount paid to each employee. A controlled calculation identifies:
- Basic salary and fixed contractual allowances
- Overtime, night-work pay, bonuses and variable allowances
- Taxable and non-taxable treatment supported by current rules and evidence
- Employee compulsory-insurance contributions where applicable
- PIT withholding based on residency and permitted deductions
- Lawful deductions, advances and the resulting net pay
Do not validate payroll by checking a few net amounts. The review pack should show employee-level and total variances against the previous month, new and terminated employees, large movements, negative or zero net pay, bank-account changes and manual overrides.
4. Apply 2026 statutory parameters carefully
From 1 January 2026, monthly regional minimum wages are VND 5.31 million in Region I, VND 4.73 million in Region II, VND 4.14 million in Region III and VND 3.70 million in Region IV under Decree 293/2025/NĐ-CP. The applicable region follows the employer’s operating location, with specific rules for units spanning different areas.
For resident employment income in tax year 2026, the family deduction is VND 15.5 million per month for the taxpayer and VND 6.2 million per month for each eligible dependant. The new PIT law also uses five progressive brackets for employment income. Payroll teams should control the effective date, residency, dependant evidence and any year-end reconciliation rather than changing only one spreadsheet rate.
Insurance treatment depends on the employee category, nationality, contract and current rules. From 1 July 2026, Vietnam Social Security states that the maximum monthly salary base linked to the reference/base salary is VND 50.6 million for compulsory social and health insurance. Confirm the applicable contribution components and bases for each employee group.
5. Approve payroll and protect the payment step
The payroll preparer should not be the sole person able to change employee bank details, approve the payroll and release payment. A company approver should review total employer cost, net pay, material movements, joiners, leavers and bank changes. The bank upload should be reconciled to the approved net-pay file and protected from unrecorded edits.
Payslips should use a controlled delivery method. Because payroll contains sensitive personal data, access should follow role and need. Keep a record of the file version that was approved and the version that was paid.
6. Reconcile after payment
Close the cycle by reconciling the payroll register to the bank result, general ledger and insurance or PIT records. Track rejected transfers, retroactive changes and statutory differences as open items with an owner and deadline. Correcting the master data is as important as correcting the amount; otherwise the same issue will repeat next month.
Monthly control checklist
- All joiners, leavers and salary changes have an approved effective date.
- Attendance exceptions and overtime are approved by the responsible manager.
- Insurance and PIT populations are reconciled to employee master data.
- Previous-month variances and manual overrides are explained.
- Payroll total, bank file and accounting entry agree.
- Late changes and post-payroll corrections are logged and approved.
Frequently asked questions
Can the cut-off date change every month?
It can, but frequent changes increase omissions and urgent corrections. Publish an annual calendar and use a defined exception process for unavoidable late data.
Who should approve the payroll?
An authorised company representative who understands the changes and total cost. A provider can calculate and review, but should not replace the client’s management approval or bank authority.
What should the provider deliver?
At minimum, a payroll register, gross-to-net detail, payslips, bank-payment data, insurance and PIT summaries, a previous-month variance report and an open-query list, subject to the agreed scope.
Official references
- Labour Code No. 45/2019/QH14, Government Gazette
- 2026 regional minimum wages, Ministry of Home Affairs information portal
- 2026 PIT family deductions, Government policy portal
- Insurance bases from 1 July 2026, Vietnam Social Security