Reviewed: 28 July 2026
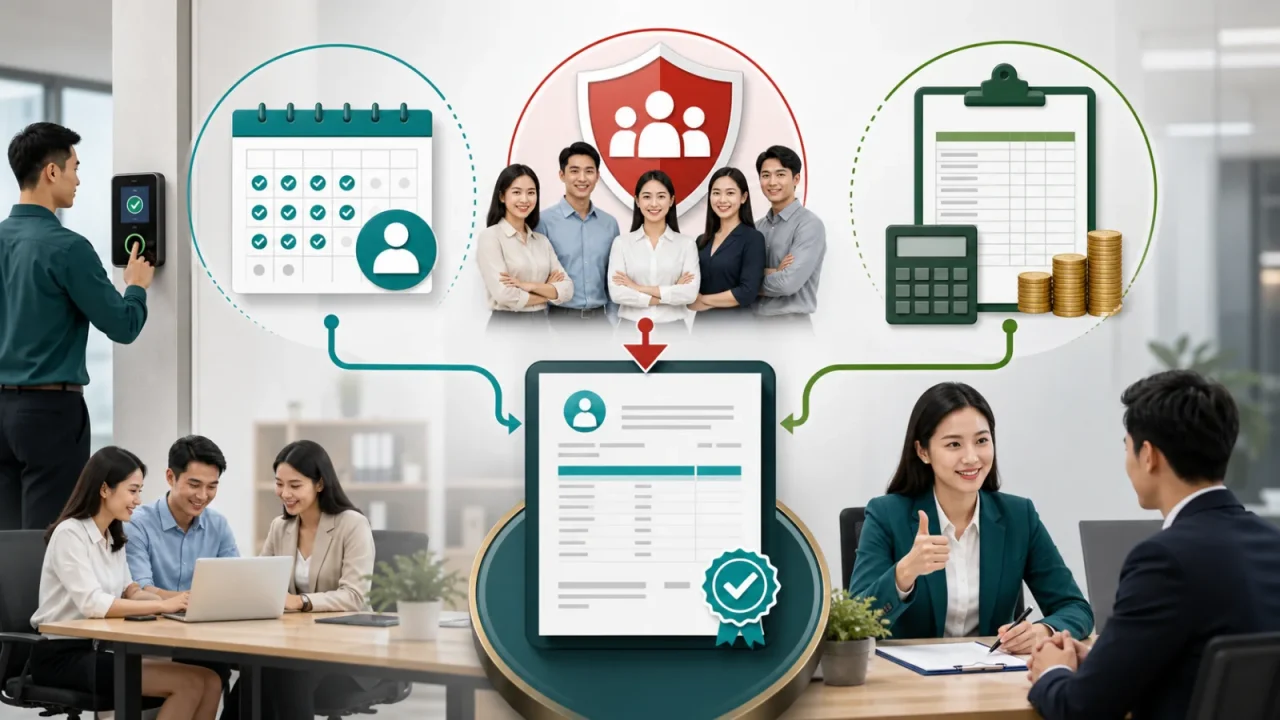
Attendance, compulsory insurance and personal income tax (PIT) are often managed by different people, but payroll connects all three. An overtime category changes pay; a salary or employment-status change can affect insurance; residency and dependant information can change PIT. Accurate payroll therefore depends on one controlled employee record and clear effective dates.
This guide explains the operational links and highlights 2026 parameters that payroll teams should validate. It does not replace an employee-by-employee assessment.
How the three data sets connect
| Source event | Payroll effect | Insurance/PIT effect |
|---|---|---|
| Joiner or leaver | Proration, final pay, unused balances | Coverage dates, withholding and finalisation data |
| Salary or allowance change | Gross pay and employer cost | Review contribution base and taxable treatment |
| Overtime or night work | Premium calculation | Review current tax treatment and evidence |
| Unpaid leave or absence | Reduced pay or no-pay days | Potential effect on contribution and reporting status |
| Dependant change | No gross-pay change | PIT deduction only after eligibility and evidence checks |
The employee master should hold the effective date, authorised source and owner for each change. The payroll file should consume that approved record rather than asking teams to re-enter the same information.
Attendance controls under Vietnam labour rules
The Labour Code generally limits normal working time to eight hours per day and 48 hours per week. Where working time is arranged by week, a normal day may be up to ten hours while the 48-hour weekly limit remains. Overtime requires the statutory conditions and employee consent, subject to exceptions, and is generally capped at 40 hours per month and 200 hours per year, with specified cases permitted up to 300 hours.
Minimum overtime pay differs by category: at least 150% on an ordinary working day, 200% on a weekly rest day and 300% on a public holiday or paid-leave day, excluding the ordinary holiday or leave pay for employees paid by the day. Night work and overtime at night have additional rules. The exact calculation needs the employee’s pay basis, work schedule and facts.
Attendance data to retain
- Scheduled and actual start/end times, break rules and location or shift where relevant
- Ordinary hours, weekday overtime, rest-day overtime, holiday work and night work as separate categories
- Paid leave, unpaid leave, sickness, maternity-related absence and other authorised absence
- Manager approval, reason for manual change and the original audit trail
- Cut-off status and a list of adjustments carried to the next payroll
Biometric or location-based attendance may also involve personal data. Apply necessity, access and retention controls rather than collecting more data than the stated purpose requires.
Compulsory insurance: avoid one universal percentage
Vietnam’s Social Insurance Law No. 41/2024/QH15 has applied since 1 July 2025. Coverage and contribution treatment depend on factors including employee category, nationality and contract. For workers in scope of the standard compulsory social-insurance regime, the core social-insurance components include an 8% employee contribution to the retirement and survivorship fund, while employer components include 14% for retirement and survivorship, 3% for sickness and maternity, and generally 0.5% for occupational accidents and diseases. Health and unemployment insurance must be assessed separately under their applicable rules.
Do not present the commonly quoted combined totals as applying to every employee. Foreign workers, Vietnamese workers, managers and different contracts can have different coverage. The contribution salary also needs to be tested against the employment arrangement, statutory floors and caps.
Important 2026 parameters
Vietnam Social Security reported that from 1 July 2026 the base/reference salary is VND 2.53 million. The maximum monthly salary base equal to 20 times that amount is therefore VND 50.6 million for compulsory social and health insurance where this cap applies. Regional minimum wages increased from 1 January 2026 to VND 5.31 million, 4.73 million, 4.14 million and 3.70 million for Regions I to IV respectively.
Each month, reconcile the employee master to the insurance population, contribution salary and joiner/leaver/amendment status. Keep submission receipts and unresolved cases separate from completed records.
PIT for employment income in tax year 2026
The Personal Income Tax Law No. 109/2025/QH15 applies from 1 July 2026, with its employment-income provisions applying from tax year 2026. For a resident individual, taxable employment income is calculated after eligible deductions. The family deductions are VND 15.5 million per month for the taxpayer and VND 6.2 million per month for each eligible dependant.
| Monthly taxable income after deductions | Rate |
|---|---|
| Up to VND 10 million | 5% |
| Over VND 10 million to VND 30 million | 10% |
| Over VND 30 million to VND 60 million | 20% |
| Over VND 60 million to VND 100 million | 30% |
| Over VND 100 million | 35% |
The rate table is only one part of the calculation. Payroll needs a documented residency position, eligible dependant records, treatment of benefits and allowances, insurance deductions and any information needed for annual finalisation. A non-resident is assessed under separate rules and should not be placed into the resident progressive table automatically.
A monthly three-way reconciliation
- Reconcile active employees, joiners and leavers across HR, payroll, insurance and PIT records.
- Compare contractual salary and approved changes to payroll and contribution bases.
- Compare attendance categories to overtime and absence values in payroll.
- Compare payroll insurance deductions and employer cost to the filing or payment working files.
- Compare PIT withholding to residency, dependant and taxable-benefit records.
- Record differences, owner, deadline and whether correction belongs in the current or next period.
Common failure patterns
- A salary increase reaches payroll but not the insurance register.
- A leaver is removed from attendance but remains in a statutory population.
- Overtime hours are supplied without day type or approval.
- A dependant is deducted before eligibility and evidence are confirmed.
- Manual corrections change net pay without updating master data or the audit trail.
- Payroll files are shared broadly or retained indefinitely without a documented purpose.
Frequently asked questions
Does the 50.6 million VND cap apply to every insurance component?
No universal assumption should be made. The official update links it to compulsory social and health insurance based on the reference/base salary. Unemployment insurance and employee-specific coverage require a separate check.
Can payroll use the same insurance treatment for local and foreign employees?
No. Nationality, contract and coverage conditions matter. Maintain explicit employee classifications and validate them when a contract or role changes.
Should old employee payroll data be kept forever?
No. Retention should follow applicable legal requirements and an agreed business purpose. Vietnam’s personal-data law requires particular attention to employee-data retention and deletion after termination, subject to legal or agreed retention grounds.
Official references
- Labour Code No. 45/2019/QH14
- Social Insurance Law No. 41/2024/QH15
- Insurance bases from 1 July 2026, Vietnam Social Security
- 2026 PIT family deductions, Government policy portal
- Personal Data Protection Law No. 91/2025/QH15